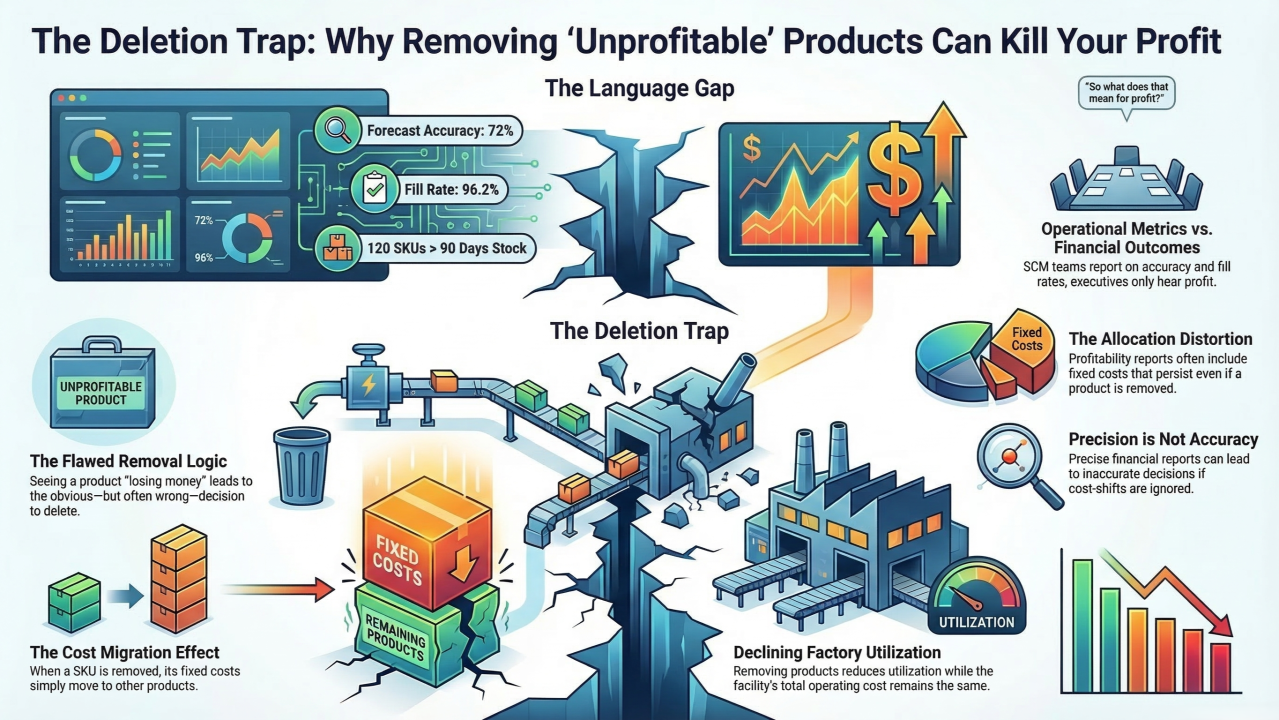
The Deletion Trap
SCM speaks in metrics.
The boardroom hears profit.
The supply chain team presents the monthly review.
Forecast accuracy: 72%
Fill rate: 96.2%
Inventory turns: +0.3
120 SKUs above 90 days of stock cover.
All accurate.
All operationally meaningful.
The CEO asks one question.
“So what does that mean for profit?”
:
This moment repeats itself in boardrooms everywhere.
The problem is not data.
It is language.
Supply chains report in operational metrics.
Executives make decisions in financial outcomes.
Between those two perspectives, translation rarely happens.
An analyst can bridge the gap in a spreadsheet.
But doing it continuously —
across thousands of SKUs, locations, and channels —
at the moment decisions are made?
That is where most organisations struggle.
And the language gap runs deeper than timing.
The word "profit" itself rarely means the same thing to everyone in the room.
Most SKU-level profitability reports are built on absorption costing —
indirect costs allocated through multiple layers: factory overheads to lines to products, warehouse costs to temperature zones to products, corporate overheads to categories to products.
The allocation basis determines the answer.
Use revenue share, and one set of products appears profitable.
Use production hours, and the picture shifts.
Use volume, and it shifts again.
The same product can appear profitable or loss-making depending on which key was chosen.
And this is where many organisations fall into what I call the Deletion Trap.
A product appears unprofitable.
The logical response: remove the SKU.
The numbers look precise.
But precision and accuracy are not the same thing.
When that product disappears, the costs it was absorbing do not.
They move elsewhere.
The remaining portfolio absorbs them.
The upside is capped: the maximum possible improvement equals exactly the contribution that product was generating. No more.
The downside is open-ended.
Factory utilisation declines, yet the cost of running that facility does not. The same fixed cost is now carried by fewer products — and products that were previously profitable may cross into loss.
Sometimes removing a loss-making product improves profit.
Sometimes it does nothing.
And sometimes it makes the situation worse.
The Deletion Trap is not an accounting error.
It is a decision-structure problem.
This is why cost layers matter for supply chain decisions.
At the variable margin level: does every unit sold cover its direct costs?
At the product contribution level: does this product generate cash after its own direct costs?
At the fully allocated level: does it show a profit after absorbing indirect overheads?
The first two layers are actionable.
The third is informative — but dangerous as a basis for deletion decisions.
Yet in many organisations, the third layer is exactly where the decision is made.
Even when the right layer is identified, simulation demands a cost table that reflects current reality. Design-stage assumptions erode within months as materials, energy, yields, and transport rates shift. The cost drivers sit across manufacturing execution, logistics, and procurement systems — mostly outside ERP. Building the cost table is a project. Keeping it current is an infrastructure problem.
The same allocation distortion does not only affect which products organisations remove.
It also affects which products they prioritise.
And that requires a very different lens.
That will be the focus of the next post.
#SupplyChain #SupplyChainManagement #OperationsStrategy #SupplyChainAnalytics #DecisionScience